When I moved into my first Austin apartment in August 2020, my lease required renters insurance. I set it up, paid the first month, and then let it quietly lapse about four months later because money was tight and it felt like the easiest thing to cut. I told myself nothing bad was going to happen. Then one night in early 2021 a pipe burst in the unit above Jake’s room and water came through the ceiling. Nothing was destroyed. But it was close. That was the night I understood what renters insurance was actually for and why I had been an idiot to cancel it.
I want to tell you about that night because I think it explains renters insurance better than any definition ever could.
It was a Wednesday in February 2021. I remember because I had just finished a late study session and was getting ready for bed around midnight. Jake knocked on my door and said there was water dripping from his ceiling. Not a little drip. A steady stream coming through the light fixture above his desk.
We called the emergency maintenance line immediately. While we waited I helped Jake move his laptop, his external hard drive, his textbooks, everything off his desk and onto his bed away from the wet area. His desk chair was already soaked. The carpet under his desk was completely wet.
Maintenance came within 40 minutes and shut off the water to the unit above. The pipe had cracked in the wall. The people upstairs were not even home, so nobody had noticed until it had been running for who knows how long.
By the time it was over, Jake’s desk chair was ruined. The carpet needed professional drying. His desk itself had water damage along the back edge. The ceiling had a stain that took weeks to repair properly.
Jake had renters insurance. He filed a claim and got reimbursed for the chair and the desk damage after his deductible.
I sat there that night thinking about my own room. My laptop. My external drives with years of work on them. My clothes. My books. If that pipe had been above my room instead of Jake’s, I would have had nothing. No insurance. No claim, Just loss.
I signed back up for renters insurance the next morning.
What Renters Insurance Actually Covers
I think a lot of people skip renters insurance because they do not really understand what it does. I know that was true for me. I thought it was some kind of optional extra that mostly benefited the landlord. I was completely wrong about that.
Renters insurance covers three main things and all three of them are for you, not your landlord.
Your personal belongings. If your stuff gets damaged or stolen, renters insurance pays to replace it. Fire, water damage from a burst pipe, theft, certain weather events. Your laptop, your furniture, your clothes, your phone. All of it can be covered up to your policy limit.
Liability protection. This is the one people forget about. If someone gets hurt inside your apartment and they decide to sue you, renters insurance covers your legal costs and any damages up to your policy limit. If you accidentally flood your downstairs neighbor’s apartment and they sue you for the damage to their belongings, your liability coverage handles it.
Temporary housing. If your apartment becomes unlivable because of a covered event like a fire or serious water damage and you need to stay somewhere else while repairs happen, some policies will cover your hotel or temporary housing costs.
Your landlord’s insurance covers the building itself. The walls, the roof, the structure. It does not cover anything inside your apartment that belongs to you. A lot of first-time renters do not know that distinction and assume the building’s insurance has them covered. It does not.


How Much It Actually Costs
This is where people are usually surprised in a good way. Renters insurance is genuinely cheap. Way cheaper than most people expect.
When I signed back up in February 2021 I went with a basic policy through Lemonade, which is popular in Austin and has a straightforward app. Here is what I got and what it cost
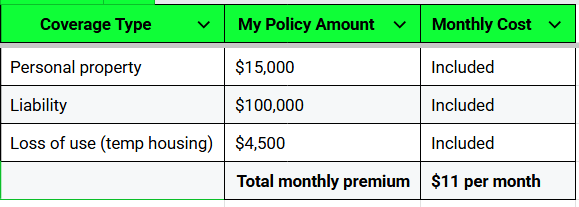
Eleven dollars a month. That is less than two coffees. For $11 a month I had $15,000 in personal property coverage and $100,000 in liability protection.
I had cancelled that policy to save $11 a month. I had put everything I owned at risk to save $132 a year. Looking back at that decision now I genuinely cannot explain the logic I was using at the time.
Why I Cancelled It in the First Place
I want to be honest about this because I think a lot of people do the same thing and the reasoning feels sensible in the moment even when it is not.
By November 2020 I was about three months into my first semester. My stipend was covering rent and food but not much else. I was going through my monthly expenses looking for anything I could cut temporarily while I waited for a small research payment to come through.
Renters insurance was $11 a month. It felt invisible. I had set it up and forgotten about it. Nothing bad had happened. The apartment felt safe. I told myself I would sign back up in a month or two when things loosened up financially.
I did not. One month became two, became three, became almost four months of having nothing. And the whole time I was living with Jake whose laptop alone was worth $1,800 sitting on a desk under a ceiling with a pipe slowly weakening above it.
The uncomfortable truth is that insurance feels pointless right up until the moment it is not. And by then it is too late to go back and buy it for the thing that already happened.
What Jake’s Claim Actually Looked Like
I asked Jake if I could share the rough numbers from his claim because I think real numbers help more than vague descriptions.
His desk chair was a mid-range office chair he had paid $280 for. His desk had water damage along the back panel. The desk itself was not destroyed but it was damaged enough that he documented it.
His deductible was $250. That means he paid the first $250 of any claim himself and the insurance covered the rest.
The total claim came to about $420 for the chair and the desk damage combined. He paid his $250 deductible. Insurance covered the remaining $170. Not a huge payout. But his chair was replaced and the process was simple enough that he did not have to argue with anyone or spend hours on the phone.
The bigger value was knowing that if his laptop had been on that desk and been destroyed, his policy would have covered up to $15,000 in personal property. A laptop, some hard drives, a monitor, some books. That all adds up fast.
What to Look for When You Get a Policy
Not all renters insurance policies are the same and a few things are worth paying attention to when you compare options.
Actual cash value versus replacement cost is the biggest one. Actual cash value means if your two year old laptop gets damaged, they pay you what a two year old laptop is worth today, not what a new one costs. Replacement cost means they pay you enough to buy the equivalent new item. Replacement cost policies cost a little more but they are worth it if you have newer electronics or furniture.
Check what events are covered. Most standard policies cover fire, water damage from burst pipes, theft, and vandalism. Flooding from outside, like a river overflowing or heavy rain coming in, is usually not covered under a standard policy. You need separate flood insurance for that.
Check the liability limit. $100,000 is a common minimum. Some people go higher especially if they have guests over regularly or have a dog.
And check the deductible. A $500 deductible means lower monthly payments but you pay more out of pocket when you actually make a claim. A $250 deductible means slightly higher monthly payments but less out of pocket when something happens.
FAQ
What is renters insurance and do I really need it?
Renters insurance covers your personal belongings if they get damaged or stolen, protects you if someone gets hurt in your apartment and sues you, and sometimes covers temporary housing if your place becomes unlivable. Your landlord’s insurance covers the building but not your stuff. Yes, you really need it.
How much does renters insurance cost in Austin?
Usually between $10 and $20 a month for basic coverage. The exact amount depends on how much personal property coverage you want, your deductible, and the company you choose. It is genuinely one of the cheapest forms of insurance you can buy.
What happens if my lease requires renters insurance and I cancel it?
Some leases allow the landlord to add you to their own master policy and charge you for it at a much higher rate if they find out your personal policy lapsed. Always check your lease for the exact language. It is almost always cheaper to just keep your own policy active.
Does renters insurance cover my roommate’s stuff too?
Usually not automatically. Most standard policies only cover the named person on the policy. Your roommate needs their own separate policy to cover their belongings. Some companies allow you to add a roommate to your policy but ask specifically before assuming.
What is the difference between actual cash value and replacement cost coverage?
Actual cash value pays you what your damaged item is worth today after depreciation. Replacement cost pays you enough to buy a new equivalent item. Replacement cost policies cost a little more per month but can make a big difference when you actually file a claim.
Can I get renters insurance if I have no US credit history?
Yes. Some companies like Lemonade do not heavily weigh credit history the way traditional insurers do. Prices may vary slightly but renters insurance is generally available to international students and new arrivals without established US credit.
What should I do right now if I do not have renters insurance?
Get a quote today. Lemonade, State Farm, and USAA are all options available in Austin. Most policies can be set up online in under 15 minutes. If your lease requires it you may already be in violation. If it does not require it, you should still have it. Eleven dollars a month is not worth gambling everything you own on nothing bad happening.